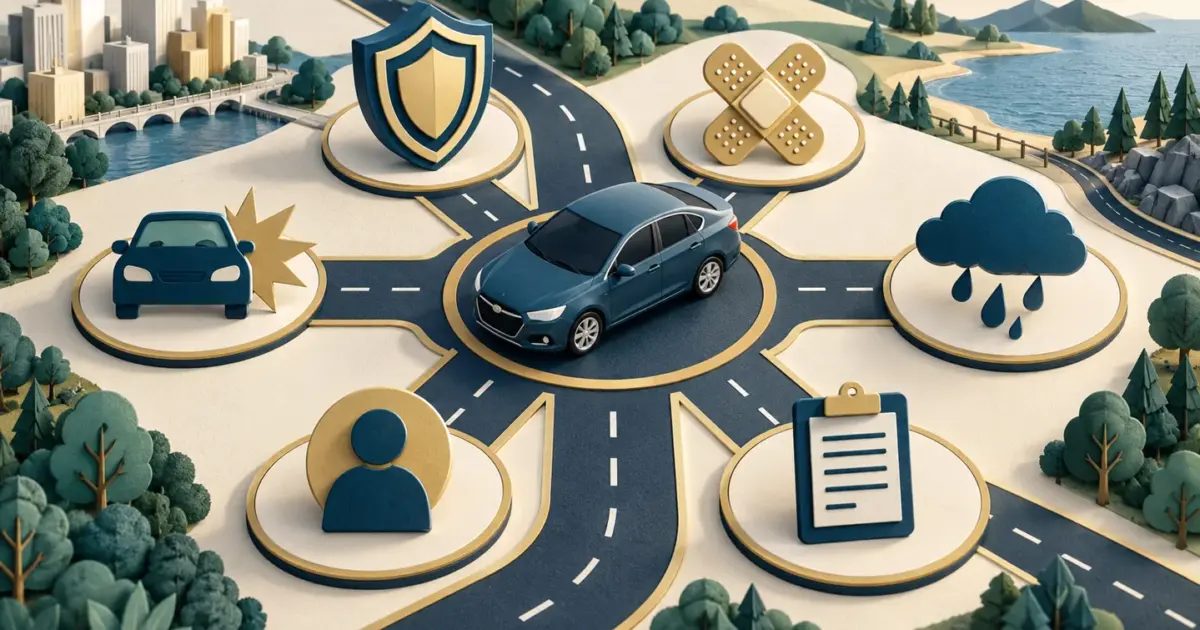
Automobile insurance serves as a vital tool for managing the financial repercussions of covered accidents, liability claims, and other vehicle-related losses. For consumers, understanding a policy goes beyond its name and requires a detailed examination of coverage limits, deductibles, exclusions, and state-specific requirements.
Deciphering Coverage Types
An auto insurance policy comprises several distinct coverages, each with specific conditions. Bodily-injury and property-damage liability coverages typically address harm for which the policyholder is legally responsible to others. These limits are crucial, as serious losses can exceed the purchased amount.
For protecting one's own vehicle, collision coverage addresses damage from accidents, while comprehensive coverage handles other types of vehicle loss, such as theft, fire, or natural disasters. Injury-related coverages like Personal Injury Protection (PIP) or medical payments, alongside uninsured or underinsured motorist protection, also offer specific protections for occupants and vehicle owners.
Key Financial Terms and Factors
When evaluating insurance offers, it is important to distinguish between key financial terms. The "premium" is the total cost of the policy. A "deductible" is the amount a policyholder pays towards a covered claim before the insurer contributes. A "limit" represents the maximum amount payable under a particular coverage provision. Confusing these numbers can lead to misjudging an offer's true value.
Liability limits are often displayed in a three-number format, for example, 100/300/100. This translates to $100,000 for bodily injury per person, $300,000 for bodily injury per accident, and $100,000 for property damage per accident. It is important to confirm with an agent how these specific limits apply to different types of claims. Factors influencing the premium include accurate driver and vehicle information, vehicle usage, and the selected coverage options.
Managing Your Policy and Claims
When comparing quotes, it is advisable to change only one variable at a time, such as a deductible or liability limit, to clearly understand its impact on the premium. Keeping a baseline quote and clearly labeled alternatives helps in this process.
To prepare for potential claims, policy documents, proof of insurance, and the insurer’s claim contact details should be stored in an easily accessible location. Additionally, retaining vehicle photographs and relevant receipts is recommended. After an incident, immediate safety concerns should be addressed first, followed by prompt contact with the insurer and adherence to reporting requirements. Maintaining a detailed record of communications and avoiding assumptions about authorization for repairs or other expenses until confirmed by the insurer are important steps. Policyholders should also review their contract at renewal and after significant life changes, such as moving, adding a driver, or replacing a vehicle, to ensure their coverage remains appropriate.
No comments yet. Be the first to share your thoughts.